The order is worth ₹1,500. It looks like a good sale—until someone searches for the item, replaces damaged packaging, corrects an address and pays for another delivery attempt.
A sales total does not show what the business keeps. To understand whether more online orders will help, follow one order from payment to completed delivery and record the work it consumes.
What should you include in the order cost?
Use a consistent basis. In the illustrative example below, sales are after customer discounts and exclude tax. Product cost and channel or payment fees are counted first; advertising, fixed rent and general overhead are not included yet.
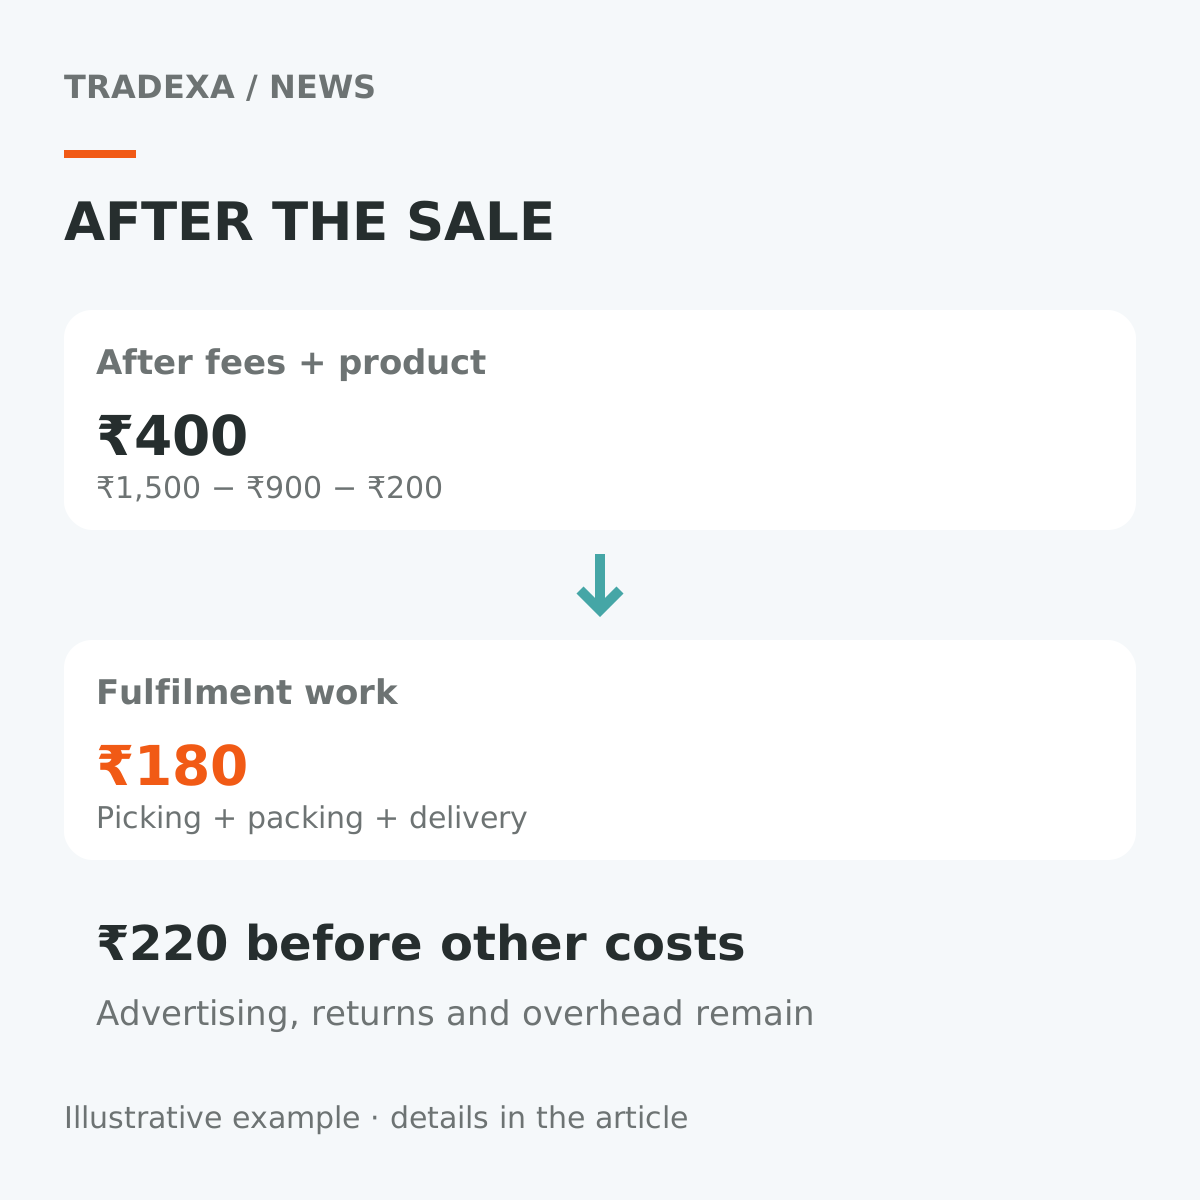
A ₹1,500 sale has ₹900 product cost and ₹200 channel and payment fees. That leaves ₹400 before fulfilment.
Now include ₹20 picking capacity, ₹25 packing capacity, ₹35 packaging and ₹100 delivery. These total ₹180, leaving ₹220 before advertising, returns and other business costs. The two labour amounts value staff time; they are not necessarily extra cash paid for this order.
Use your actual fee and courier records. Avoid counting a cost twice if it is already included in a settlement deduction or another category.
Copy this per-order cost worksheet
Use one order reference and one consistent tax basis. For a retained sale, record:
- Net sales: after customer discounts and refunds, excluding tax. Example: ₹1,500.
- Product cost: cost of goods sold on the same basis. Example: ₹900.
- Channel and payment fees: applicable charges. Example: ₹200. List what this includes before entering courier fees elsewhere.
- Fulfilment cash costs: packaging ₹35 and delivery ₹100 here.
- Staff capacity: picking ₹20 and packing ₹25. Keep the minutes as well as their chosen value.
- Exceptions and advertising: actual extra courier/packaging charges, recovery time and advertising allocation. Mark unknown costs unknown, rather than zero.
- Remainder: ₹1,500 − ₹900 − ₹200 − ₹35 − ₹100 − ₹20 − ₹25 = ₹220 before line six and fixed overhead.
Add an outcome: delivered and retained, cancelled, failed delivery or returned. For a refunded order, net sales may be zero while outbound freight and handling remain. Record recoverable stock separately; do not charge its full purchase cost as a permanent loss when the item is saleable again. Damaged stock, return freight and non-refundable fees need their own treatment.
For a monthly view, total retained net sales and all relevant costs—including failed orders—then divide by total attempted orders for a per-attempt measure. Averaging only successful parcels hides the rest of the operation. Agree recoverable-stock, tax and refund treatment with finance.
Follow the exception, not just the parcel
Watch the exceptions, not only the smooth orders. A missing item, incorrect variant or incomplete address can require a second check, a customer conversation and another dispatch.
Suppose 30 of 1,000 monthly orders need an additional 15 staff-minutes each. That is 7.5 staff-hours a month. Suppose 20 cases arise from a missed product-location or variant check and ten have other causes. If a location check and a clearer dispatch handoff prevent those 20 cases, five hours become available for other work. Record the actual causes before selecting that improvement target.
At unchanged volume, that is 60 staff-hours a year. Ten exceptions remain; ordinary picking, packing and delivery still happen. Record what actually improves before budgeting a benefit.
Those five monthly hours can go into dispatching the next orders rather than recovering yesterday's mistakes. Check whether picking, packing or courier collection is the actual bottleneck before converting the hours into a higher order target.
Are you comparing similar orders?
A small prepaid parcel and a bulky product with a second delivery attempt are not equivalent. Group orders by the factors that change costs: package size, delivery destination, item count and exception type.
Keep cancelled orders and returns visible too. Returned stock is not necessarily ready for resale, and an order that produces no retained sale can still use courier and staff resources.
If one product's ₹220 remainder is routinely consumed by advertising or rework, increasing its order volume may increase activity without improving the business. Another product may support growth with less recovery work.
Fix one repeated exception first
Choose a frequent cause, record its monthly cases and measure the tasks involved. Change the product, picking or dispatch process, then compare the same measures over a similar period.
HyperInventory supports order and shipment operations, warehouse workflows and pick lists. Pick lists organise the warehouse handoff; the worksheet keeps courier charges and remaining exceptions visible.
Once you know what an order leaves behind, use that contribution in your channel pilot and your advertising margin check. The worksheet measures fulfilment economics; those decisions determine where worthwhile new orders should come from.
Example note: The numbers illustrate a scenario, not measured customer results. Actual outcomes vary with business type, category, demand, competition, team, processes, business setup, external conditions and how effectively the workflow is used. Replace the example inputs with your own before making a decision.